
Fed Balance Sheet at 21% of GDP: Central Banks Deflate, Liquidity Persists

 Prefer us on Google


Stored away, the pipe from 2020. Not cut. The latest weekly report from the Fed (H.4.1, published every Thursday) confirms the trend that has been underway for two years: major central banks are deflating their balance sheets inflated by Covid, each at its own pace. However, this has nothing to do with a return to the pre-2020 world. Key points of this article: * Major central banks, including the Fed, have deflated their massive balance sheets accumulated during the Covid crisis, marking a notable change from 2020. * The U.S. Treasury has taken over from central banks by purchasing debt to influence market liquidity, a role previously played by the Fed. According to the Federal Reserve, its assets accounted for 21% of U.S. GDP at the end of March 2026, down from a peak of nearly 37% in 2021. The balance sheet remains considerable: approximately $6.73 trillion as of August 26, according to the latest H.4.1 report cited by The Kobeissi Letter. Thus, it is far from negligible. In the spring of 2020, the Fed doubled its balance sheet in a few months to prevent the collapse of the U.S. bond market. Six years later, the urgency has disappeared. The stock of accumulated assets has remained on the books. A similar movement is seen elsewhere, albeit at different speeds. The ECB has fallen below 40% of Eurozone GDP, a first since the first quarter of 2020, far from the 65% reached in 2022. The Bank of Japan still hovers around 103% of Japanese GDP, down from a peak of nearly 130% in 2021. As the guardian of the world's most massive quantitative easing program, the BoJ is deflating. Nevertheless, it still holds a colossal lead over its Western counterparts. The Bank of England has dropped to about 21% of British GDP, a floor not seen since 2016, after peaking at 40% in 2021. And while the post-Covid stimulus has largely faded, liquidity has not disappeared. It has simply changed taps. Quantitative tightening (QT, the voluntary reduction of a central bank's balance sheet) is over or has significantly slowed in most areas. Bank reserves are still described as "ample" by the Fed itself, preventing any hiccups in the repurchase agreement (repo) market, where the fall of 2019 had already turned into panic. Most importantly, the U.S. Treasury has taken over, with Scott Bessent now buying up to $4 billion of long-term debt per operation, while the Treasury General Account (TGA, the federal government's cash held at the Fed) hovers around $950 billion in mobilizable reserves. This allows the market to be watered without the Fed needing to reopen the pipe. This mechanism explains why the price of Bitcoin rose after the announcement of Bessent's buybacks, not after a monetary policy decision from the Fed. Confusing the two is like applauding the wrong orchestra. The channel has changed shape. It is no longer the central bank that prints; it is the Treasury buying back its own debt to loosen the grip on long-term rates. The shortcut circulating, that of a dead stimulus that would mechanically condemn Bitcoin, overlooks one detail. The asset has risen during the monetary tightening phases of the past four years, not just during QE. Its short-term price follows the net liquidity flows, those that enter and exit the system day by day, much more than the gross size of a central bank balance sheet that has been frozen for months. Central banks have stored away the pipe from 2020. The tap has now passed to the Treasury. Kevin Warsh, the new Fed chair, will hold his inaugural speech this Friday, August 28, in Jackson Hole, before a market that is paying less attention to his words on rates than to those about who, between the Fed or Bessent, will truly steer liquidity in 2027.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
FTX and AI Apocalypse: The End of Calm Times for Anthropic
What is CBDC? Governments Push for Development of Central Bank Digital Currencies
Bitcoin Has Not Fallen Below Realized Price During the Bear Market
The Clearing House Selects Quant for US Tokenized Deposit Network
4500 Bitcoins Moved to New Addresses, Sale Status Unconfirmed
[New York Gold, Bonds, Dollar] Interest Rates and Dollar Strength Pause... Oil Prices Drop, Won and Gold Prices Rebound
Trump Expresses Concern Over Yen Depreciation, Japanese Finance Minister Says Coordination with U.S. Will Continue
Treasuries at 21-Year High: Impact on Stocks and Interest Rates
Solana DEX volume spike hides circular trades, and automated bots are blamed
Oracle Stock vs. KRAFTON Stock: Why Are Investors Questioning Two Growing Companies?
Compare Oracle and KRAFTON stocks through their latest results, share-price questions and the different growth tests investors face in 2026.
John Templeton: "Bull markets are born in pessimism"
The Death of Hsin-Ju: A Prelude to Conspiracy
LTC Airdrop 2026: How to Claim 50,000 USDT Rewards on WEEX
Raiffeisen’s crypto deal could reach 18 million customers. How many can actually trade?
TRON Surpasses $30T in Total Transaction Volume as it Secures its Place as Leading Chain for Stablecoins
HTX DeepThink: Opportunities Concentrate on Profitable and Fund-Supported Assets, BTC Still Has Room for Recovery After Consolidation
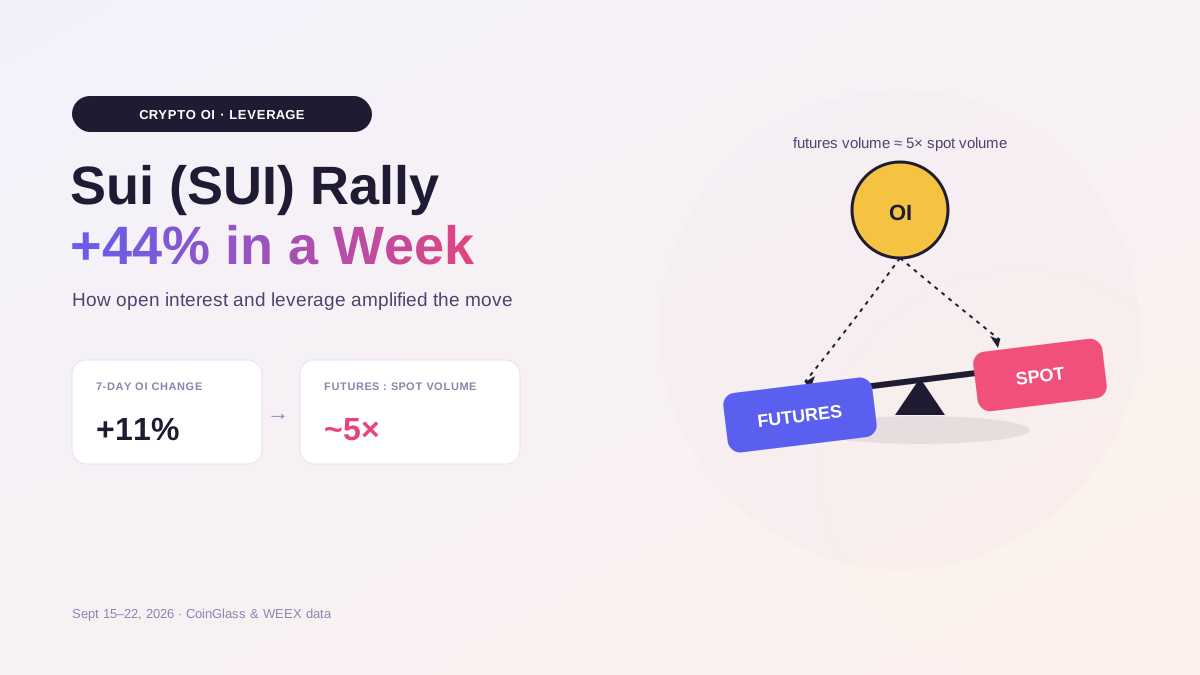
Why Did Sui (SUI) Crypto Price Jump 44%? Crypto OI and Leverage Explain the Rally
See why Sui (SUI) jumped 44%, how crypto OI and leverage amplified the rally, what the pullback means, and how to trade SUI on WEEX.
Circle expands CCTP to EURC and cirBTC on Arc
Bitcoin, Sports, and Politics: Predictive Markets Target $10 Trillion
AI Agent Jev Expects On-Chain Innovation Through Automated Judgment
The End of the Blank Prompt: Why Trading AI Needs a Playbook
Stablecoins hold nearly $200 billion in US debt, but money funds bought the surge
How Did a Hacker Create 46 Billion Fake Bitcoin in the Symbiosis Exploit? Decodes Bitcoin Hacker With WEEX Now
How two Symbiosis bridge bugs let a hacker mint 46.1 billion unbacked syBTC, drain Bitcoin pools and expose critical bridge risks.
CFTC's Selig Emphasizes the Need to Prepare for the Era of Large-Scale Tokenization in the U.S.
The IMF opens an office in Venezuela to supervise an economy that has already migrated to USDT
SOXL Stock Jumped 12% Yesterday: Three Companies Explain the Entire Move
Bitcoin's Hashrate Rises as Miners Reactivate Their Machines
Bitcoin 2x Leveraged ETF Launches on Cboe, But Doesn't Buy Bitcoin: Here's Why
Crypto: The ECB Enters the Tokenized Bond Market
WEEX Bitcoin Weekly Outlook: Why Did Bitcoin Rebound Above $80,000 After the CLARITY Act Vote?
Bitcoin rebounded above $80,000 as SEC and CFTC action, renewed ETF inflows, and a short squeeze outweighed the failed CLARITY Act vote.
FTX and AI Apocalypse: The End of Calm Times for Anthropic
What is CBDC? Governments Push for Development of Central Bank Digital Currencies
Bitcoin Has Not Fallen Below Realized Price During the Bear Market
The Clearing House Selects Quant for US Tokenized Deposit Network
4500 Bitcoins Moved to New Addresses, Sale Status Unconfirmed
[New York Gold, Bonds, Dollar] Interest Rates and Dollar Strength Pause... Oil Prices Drop, Won and Gold Prices Rebound



