
Visa’s $2.5 billion crypto credit bet puts card settlement financing onchain

 Prefer us on Google



Every card payment creates a timing problem for the company behind it. A card program may owe Visa through daily settlement before money arrives from its customers, leaving a short but recurring funding gap.
Visa's onchain lending initiative, announced Sept. 8, targets that gap. Credit Coop, an onchain credit protocol, supplies revolving stablecoin facilities that can fund settlement and sweep later cardholder payments toward repayment.
The design brings a conventional form of receivables finance onto blockchain rails. Smart contracts handle draws, cash-flow control and repayment, while authorized Visa settlement files remain central to underwriting and facility sizing. The result is a hybrid credit market in which execution becomes more visible while the decisive commercial data and risk terms stay permissioned.
The settlement gap becomes collateral
Stablecoin-linked card programs settle obligations on Visa's schedule even when cardholders pay on a different schedule. That mismatch can be especially difficult for a young program whose transaction volume is rising faster than its access to bank credit or warehouse financing.
Visa says the funding need is growing with its stablecoin business. The company reported more than 160 stablecoin-linked card programs in its fiscal second quarter of 2026, with payment volume on those programs nearly 200% higher than a year earlier. Stablecoin settlement had also recently exceeded a $20 billion annualized run rate, more than 15 times the prior-year pace, Visa said.
Each figure measures a different part of the business. The program count describes network reach, the growth rate covers card-payment activity, and the settlement run rate annualizes a more recent flow. Credit Coop's outstanding loan principal is a separate measure. The combination still points to a growing pool of programs that may need short-duration capital against settlement receivables.
According to Visa's detailed description, a participating program draws from a stablecoin-denominated revolving facility to meet a settlement obligation. Funds move toward Visa's settlement address. Later, cardholder proceeds flow through Credit Coop's Spigot contract, a programmable lockbox that services interest and replenishes the line before remaining cash reaches the borrower's operating account.
Visa characterizes the model as secured only by settlement receivables. That description sets it apart from the familiar DeFi structure in which a borrower posts more liquid crypto collateral than the loan is worth. Here, the asset supporting the advance is the payment stream generated by cardholders.
The chain records draws and repayments, providing timestamps, token movements and a history of contract execution. Visa said Credit Coop had processed more than 3,000 borrow events and 9,000 repayment events across participating facilities.
A second evidence layer sits inside Visa. Credit Coop receives each program's authorized daily settlement files through a secure pipeline, Visa says, then uses those records with the onchain history for facility sizing, disbursement and repayment verification. Public transaction data can document token movements, while the Visa feed connects those movements to a specific settlement obligation and the program's operating performance.
That gives Visa an expanded role. Its rails create the timing gap, and its records help lenders decide how much capital should bridge it.

The track record is large, concentrated and self-reported
Visa said the Credit Coop model had financed more than $2.5 billion of cumulative settlement volume since 2023, with zero defaults. The company also said greater lender participation had reduced borrowing costs for participating programs by as much as 30%.
Both claims require careful scale. Cumulative financed settlement volume measures throughput through revolving facilities. The same capital can be advanced, repaid and used again, so the $2.5 billion figure says little by itself about principal outstanding or capital at risk on a given day. It also should not be read as Credit Coop revenue, total card spending or market share.
The provenance is equally important. Visa's companion settlement-financing explainer says Credit Coop provided the program figures and that the onchain event counts were measured as of Aug. 19, 2026. It said the zero-default status should be reconfirmed before publication. For the claimed borrowing-cost reduction, Visa supplied no facility-level rates, sample size or calculation methodology.
Rain, a payments company and Visa principal member, accounts for most of the disclosed activity. Visa said Rain has used a Credit Coop revolving facility since August 2023 and had financed about $2 billion of cumulative settlement volume through more than 2,000 borrow events and 7,000 repayments as of Aug. 19.
Three years of repeated draws and repayments show an operating system with meaningful use. The available figures reveal less about the shape of its credit risk. Starting facility sizes, current exposure, lender concentration and performance through a loss period remain outside the disclosure.
Karta offers a view of where Visa thinks this model can lead. Visa says the card company launched and scaled with Credit Coop financing before moving to a larger institutional facility.
Karta's own June announcement confirms the later capital package: a $15 million Series A and a $125 million credit facility from Community Investment Management. Its announcement does not mention Credit Coop, so Visa is the source for the link between Karta's early growth and the onchain facility.
The sequence suggests one possible role for onchain credit. Repeated settlement draws and repayments can help a smaller program build an operating history before it seeks conventional institutional capital. That makes the blockchain facility a bridge into private credit rather than a replacement for it.
Programmable priority still leaves a loss question
Credit Coop's secured-line documentation says a facility can include multiple lenders and assigns them priority repayment through Spigot-controlled cash flows. The contract enforces the configured route for money that reaches it.
Credit Coop's technical materials also identify the human and software dependencies around that promise. The protocol assigns important powers to an arbiter and a Spigot owner. Its edge-case documentation describes possible revenue-contract changes, diverted cash flows, malicious control and complications in post-default execution. Those are design risks, with no indication that they occurred in the Visa-linked facilities.
The facility-specific legal protections remain out of view. Public disclosures do not name every lender behind the Visa-linked programs or provide the complete waterfall governing losses. They leave unanswered whether borrowers contribute first-loss equity or reserves, whether guarantees or insurance apply, and how far a lender's claim extends after controlled receivables run short.
A programmable lockbox improves a lender's control over incoming value. It cannot create value when customers fail to pay or when a receivable is disputed. It also cannot route money that never enters the controlled path. Any resulting loss would depend on protections and contractual claims that Visa and Credit Coop have yet to detail publicly.
That boundary defines the experiment more clearly than the label "onchain lending." The useful product is a senior claim on payment flows, serviced at blockchain speed and informed by Visa's private records. The public chain supplies evidence of execution. Visa's data and the facility contracts determine how much that evidence says about credit quality.
This is a credible product-market fit for onchain credit because it solves a recurring financing need created by card settlement. It also strengthens Visa's position inside the market: the network supplies the rail, the crucial underwriting data and the context that turns a token transfer into a credit signal.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
OKX Star Points Out THORChain TSS + Validator Model Lacks Decentralization
Payward, the parent company of Kraken, invests billions in financial infrastructure
Bloomberg analyst warns 5% U.S. 10-year yield may reduce Bitcoin appeal
Shielded Bitcoin: the proposal that aims to bring privacy without changing BTC's code
What is CBDC? Governments Push for Development of Central Bank Digital Currencies
Backpack CEO Plans to Bring the Entire Stock Market to Solana
Use of Stablecoins Grew 75% in Bear Market
[New York Gold, Bonds, Dollar] Interest Rates and Dollar Strength Pause... Oil Prices Drop, Won and Gold Prices Rebound
Polymarket partners with OpenWorlds on AI trading agents
Former New York Governor Cuomo: Tokenization Surpasses U.S. Regulation, Regulatory Clarity Affects Capital Flow
US-Iran Negotiations Signal Easing Energy Tensions, but Diesel Crisis Complicates Inflation Risks
Thailand Stock Market News: SET and NYSE Explore Dual Listings and New Investment Products
Compute Finance: The Financial Layer Being Built by the AI Economy, 0G is Constructing a New Paradigm for Computing Assets
Wall Street Legend Bill Miller: Why Did I Bet Half My Fortune on Bitcoin?
The Stronger the AI, the Lower the Wages: Your Education is Becoming the Most Expensive Devalued Asset
Oracle Stock vs. KRAFTON Stock: Why Are Investors Questioning Two Growing Companies?
Compare Oracle and KRAFTON stocks through their latest results, share-price questions and the different growth tests investors face in 2026.
What Happens When the AI Bubble Bursts? MIT University Responds
The Value of Ethereum and the Jevons Paradox
The Real Bottleneck of Midnight's Slow Growth: It's Not the Product, It's Market Formation
IonQ Stock Surges 5%: Nvidia Just Agreed to Host Its New Quantum System
HIFI Completes $37 Million Series A Funding Led by Left Lane Capital
HIFI Completes $37 Million Series A Funding Led by Left Lane Capital
Ethereum's 'Two-Track Update': Glamsterdam Public Testnet and Hegotá Initial Validation
Exclusive Interview with Frontier Technology Investor Zheng Di: SEC's 'Innovation Exemption' Opens the Door to a Compliant Bull Market, Which Assets Are Potential Stocks?
HTX DeepThink: Opportunities Concentrate on Profitable and Fund-Supported Assets, BTC Still Has Room for Recovery After Consolidation
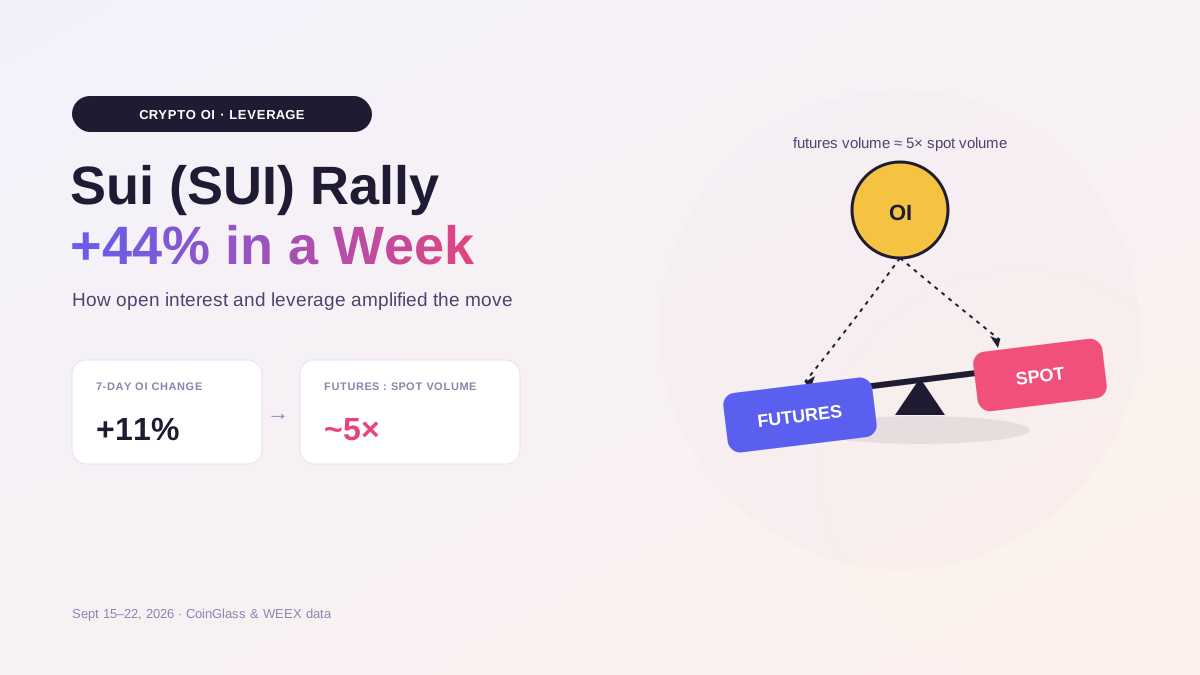
Why Did Sui (SUI) Crypto Price Jump 44%? Crypto OI and Leverage Explain the Rally
See why Sui (SUI) jumped 44%, how crypto OI and leverage amplified the rally, what the pullback means, and how to trade SUI on WEEX.
CFTC Chair Calls for "Mass Tokenization"! Wall Street Faces Three Barriers to Full On-Chain Adoption
Is the 1 Billion POL Burn Just a Joke?
WEEX Exclusive:Bitcoin Pulls Back From $87,000| WEEX TradFi Daily Brief (September 24, 2026)
Bitcoin Pulls Back From $87,000| WEEX TradFi Daily Brief (September 24, 2026)
Bitcoin pulled back from about $87,000 to about $84,000, with Ethereum near $2,680. S&P Global PMI on September 23 ET far exceeded forecasts. The 10-year yield broke above 5.00%, while the 5-year and 30-year touched highs last seen in 2007 and 2004. The S&P 500 and Nasdaq slipped. Energy moved with oil and crypto-treasury stocks followed bitcoin lower. Investors await earnings from COST, BB, and others.
OKX Star Points Out THORChain TSS + Validator Model Lacks Decentralization
Payward, the parent company of Kraken, invests billions in financial infrastructure
Bloomberg analyst warns 5% U.S. 10-year yield may reduce Bitcoin appeal
Shielded Bitcoin: the proposal that aims to bring privacy without changing BTC's code
What is CBDC? Governments Push for Development of Central Bank Digital Currencies
Backpack CEO Plans to Bring the Entire Stock Market to Solana


