
RKLB Stock: Why Simply Wall St Sees It 43% Undervalued After a $1.9 Billion Raise

 Prefer us on Google



RKLB stock has become one of the market’s most debated space growth stories. RKLB stock keeps attracting bulls because Rocket Lab posted record 2026 revenue, backlog, and liquidity, yet RKLB stock also carries heavy execution risk tied to Neutron and acquisitions. The latest twist is a third-party claim that the shares are 43% undervalued after a roughly $1.944 billion capital raise. That sounds simple, but it is not. The real question is whether a discounted cash flow model can be trusted when Rocket Lab is still burning cash and issuing more shares.
Quick Answer
- The 43% undervalued claim comes from a DCF model that assumes Rocket Lab’s free cash flow turns from deeply negative to strongly positive over time.
- The $1.944 billion raise reduces financing strain around the planned Iridium acquisition, but it also adds dilution through 29.3 million new shares.
- Simply Wall St’s undervaluation figure has shifted repeatedly in recent weeks, which shows how sensitive the model is to changing assumptions.
- DCF points to upside, while traditional valuation multiples such as price-to-sales still look extremely rich.
- Short-term price action can still fall even when a long-term model says the stock is cheap.
What Simply Wall St's 43% Undervalued Claim Is Actually Based On
The headline number comes from a discounted cash flow, or DCF, model. A DCF does not value a business based on today’s profits alone. Instead, it tries to estimate how much cash the company may generate in the future, then discounts those future cash flows back to today’s dollars.
That matters because Rocket Lab is not valued like a mature aerospace contractor. According to Yahoo Finance, the company still has no trailing twelve-month P/E ratio and reported negative EPS. The specific issue here is free cash flow. The model behind the bullish call assumes Rocket Lab can move from roughly negative $370.5 million in recent trailing free cash flow to positive and expanding cash generation over the next decade. In other words, the “cheap” label depends less on current profitability and more on a future where Rocket Lab executes at a very high level.
That is why readers should treat the 43% figure as a model output, not a fact. Simply Wall St itself states that its article is not intended as financial advice and does not constitute a recommendation to buy or sell any stock. That disclaimer is important here because the result depends heavily on assumptions about growth, margins, capital intensity, and share count.
Why the $1.94 Billion Raise Changes the Underlying DCF Story
The financing itself changes the narrative. The raise was about $1.944 billion, and the stated purpose was to fully fund the planned Iridium acquisition while reducing reliance on bridge debt. That matters because a DCF can improve if balance-sheet pressure falls. In plain English, the future cash flow story becomes more about execution and less about whether the company can afford to keep investing.
There is a real business backdrop supporting that more optimistic view. Rocket Lab reported record Q1 2026 revenue of $200.3 million, up 63.5% year over year, then followed with Q2 revenue of $234.1 million, up 62%, according to company releases. Backlog rose from about $2.2 billion at the end of Q1 to $2.36 billion at the end of Q2, and management said it had access to more than $2 billion in liquidity. Space Systems is also doing more of the heavy lifting, with Q2 product revenue of $181.3 million versus service revenue of $52.7 million.
Still, better funding does not remove the risks. It just shifts the focus. If the Iridium deal closes around mid-2027 as planned and integration goes well, the DCF story becomes easier to defend. If integration disappoints, the model can break quickly.
-- Price
Why the Same Model Has Given RKLB Wildly Different Numbers in Recent Weeks
This is the part many investors miss. The 43% undervalued claim is not a stable consensus estimate. It is one moving estimate from a third-party framework that has already produced several different numbers for the same stock in a short period.
Based on the supplied materials, Simply Wall St previously framed RKLB as about 23.6% undervalued around July 26 after a Space Force-related development. Later, similar articles cited roughly 45.8%, then 43.9%, and now about 43%, with the changes tied to fresh events such as national security momentum, NASA contract developments, and this financing round. That “number drift” is not a minor footnote. It is evidence that the model is highly sensitive to updates in assumptions.
So if you see a precise percentage attached to RKLB stock, the right response is not “the market is wrong by exactly 43%.” The better response is “what changed in the assumptions this time?”
The Valuation Split Nobody's Resolving: DCF Says Cheap, Market Multiples Say Expensive
The sharpest tension around RKLB stock is that different valuation methods are telling opposite stories.
| Valuation View | What It Suggests |
|---|---|
| DCF | Shares may be undervalued if future cash flow scales sharply over time. |
| Price-to-Book | At about 11.3x, RKLB looks expensive versus the aerospace and defense average of 3.1x, though below some high-growth space peers at 18.1x. |
| Price-to-Sales | At about 49.7x, RKLB looks far more expensive than the sector average of 4.5x, peer average of 7.9x, and even Simply Wall St’s own “fair” 11.0x benchmark. |
This is not just a math disagreement. DCF is asking what Rocket Lab might become if it scales successfully. Multiples are asking what investors are paying today relative to current sales, book value, and current losses. For a company with strong growth but no trailing profitability, those two lenses can easily clash.
Why the Stock Fell 5% the Same Day This "Undervalued" Call Came Out
The market can agree with a long-term thesis and still punish a financing event in the short term. That appears to be what happened here. Reports cited about a 5% drop after the offering, and the main concern was dilution.
That concern is straightforward. The deal adds 29.3 million new shares. Even if the cash helps fund growth or acquisition strategy, existing holders still own a smaller percentage of the company afterward. A DCF may say the enterprise becomes stronger, but the market often reacts first to the immediate hit to per-share ownership.
This is common in growth stocks. Investors may support the strategic use of capital and still dislike the timing, size, or pricing of an issuance.
What Would Actually Need to Happen for the DCF Case to Hold
For the bullish DCF case to work, Rocket Lab likely needs more than just strong headlines. It needs sustained execution across several fronts.
First, revenue growth must remain strong enough to justify today’s premium. So far, the company has delivered that, with first-half 2026 revenue reaching $434.4 million versus $267.1 million in the prior-year period. Second, Space Systems likely has to keep scaling because it is already the larger revenue engine. Third, Neutron must progress without major disruption. SEC filings repeatedly warn that development, testing, infrastructure readiness, manufacturing quality, and production rate could all affect customer acceptance, revenue, and capital needs.
That is why RKLB stock behaves like a high-volatility growth name rather than a stable industrial. Yahoo Finance lists a beta of about 2.61 and a 52-week range of roughly $37.57 to $151.00. Options positioning also reflects a speculative tone, with MarketChameleon showing call open interest of about 742,652 versus put open interest of about 517,160, a put/call ratio near 0.7.
If Rocket Lab keeps setting revenue records, converts backlog into delivered work, integrates acquisitions cleanly, and advances Neutron on schedule, the DCF argument gets stronger. If delays or cash burn persist longer than bulls expect, the same model can swing the other way.
Trade RKLB Directly on WEEX
For traders who want exposure without waiting for traditional market hours, WEEX RKLB-USDT stock trading offers a way to follow this high-volatility name more actively. That may appeal to users who already trade crypto, derivatives, or other global risk assets on a multi-asset platform. As always, the key with RKLB stock is position sizing and risk control, because the name can move sharply on earnings, contracts, launch updates, financing news, and broader sentiment around space equities.
Conclusion
RKLB stock may look undervalued in a DCF model, but that conclusion rests on aggressive future cash flow improvement, continued operational execution, and successful integration of new assets after dilution. The bigger lesson is not the exact 43% figure, but how quickly that figure changes when assumptions change.
FAQ
1. Is RKLB stock really 43% undervalued?
Only in one third-party DCF framework. That percentage is assumption-driven and has already shifted several times in recent weeks.
2. Why does a DCF model look bullish while price-to-sales looks expensive?
DCF values future cash generation, while price-to-sales focuses on what investors are paying today relative to current revenue. For unprofitable growth companies, those methods often disagree.
3. Why did RKLB stock fall after the capital raise?
The market focused on dilution from 29.3 million new shares. Short-term price action often reacts more to dilution than to long-term strategic benefits.
4. What are the main things investors should watch next?
Key items include backlog conversion, Space Systems growth, Iridium acquisition progress, and Neutron development milestones mentioned in Rocket Lab filings and earnings updates.
5. Is the Simply Wall St article investment advice?
No. Its own disclaimer says the content is not intended as financial advice and does not constitute a recommendation to buy or sell the stock.
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
OKX Star Points Out THORChain TSS + Validator Model Lacks Decentralization
Payward, the parent company of Kraken, invests billions in financial infrastructure
Bloomberg analyst warns 5% U.S. 10-year yield may reduce Bitcoin appeal
Shielded Bitcoin: the proposal that aims to bring privacy without changing BTC's code
What is CBDC? Governments Push for Development of Central Bank Digital Currencies
Backpack CEO Plans to Bring the Entire Stock Market to Solana
Use of Stablecoins Grew 75% in Bear Market
[New York Gold, Bonds, Dollar] Interest Rates and Dollar Strength Pause... Oil Prices Drop, Won and Gold Prices Rebound
Polymarket partners with OpenWorlds on AI trading agents
Former New York Governor Cuomo: Tokenization Surpasses U.S. Regulation, Regulatory Clarity Affects Capital Flow
US-Iran Negotiations Signal Easing Energy Tensions, but Diesel Crisis Complicates Inflation Risks
Thailand Stock Market News: SET and NYSE Explore Dual Listings and New Investment Products
Compute Finance: The Financial Layer Being Built by the AI Economy, 0G is Constructing a New Paradigm for Computing Assets
Wall Street Legend Bill Miller: Why Did I Bet Half My Fortune on Bitcoin?
The Stronger the AI, the Lower the Wages: Your Education is Becoming the Most Expensive Devalued Asset
Oracle Stock vs. KRAFTON Stock: Why Are Investors Questioning Two Growing Companies?
Compare Oracle and KRAFTON stocks through their latest results, share-price questions and the different growth tests investors face in 2026.
What Happens When the AI Bubble Bursts? MIT University Responds
The Value of Ethereum and the Jevons Paradox
The Real Bottleneck of Midnight's Slow Growth: It's Not the Product, It's Market Formation
IonQ Stock Surges 5%: Nvidia Just Agreed to Host Its New Quantum System
HIFI Completes $37 Million Series A Funding Led by Left Lane Capital
HIFI Completes $37 Million Series A Funding Led by Left Lane Capital
Ethereum's 'Two-Track Update': Glamsterdam Public Testnet and Hegotá Initial Validation
Exclusive Interview with Frontier Technology Investor Zheng Di: SEC's 'Innovation Exemption' Opens the Door to a Compliant Bull Market, Which Assets Are Potential Stocks?
HTX DeepThink: Opportunities Concentrate on Profitable and Fund-Supported Assets, BTC Still Has Room for Recovery After Consolidation
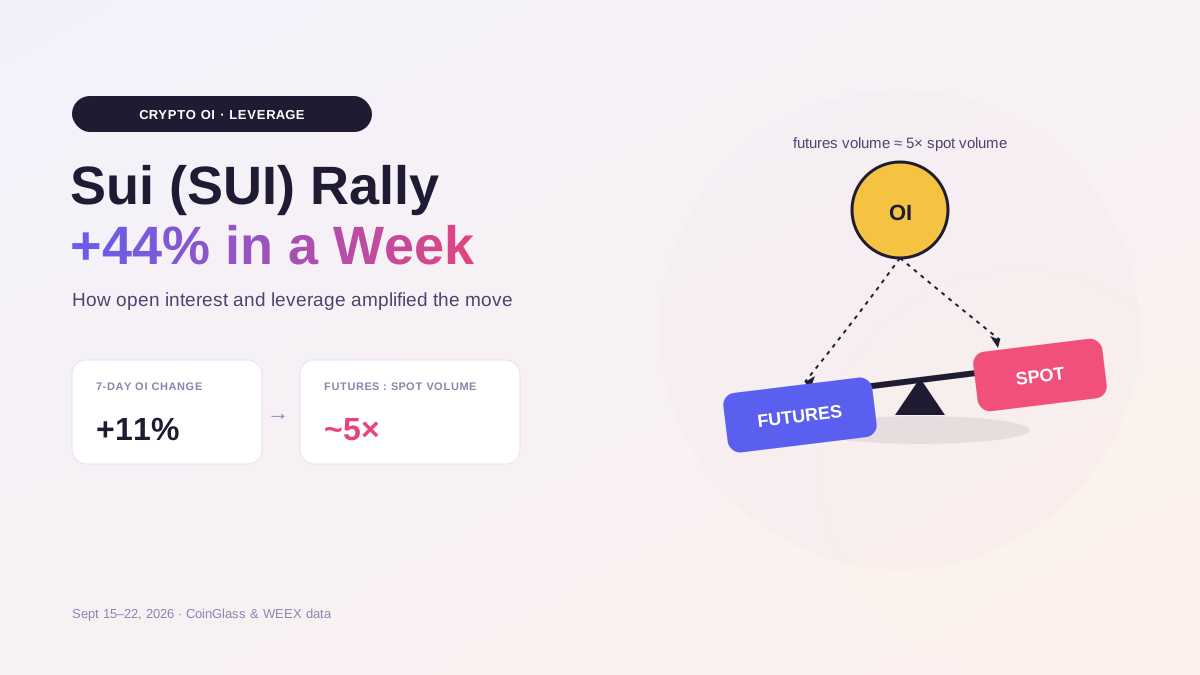
Why Did Sui (SUI) Crypto Price Jump 44%? Crypto OI and Leverage Explain the Rally
See why Sui (SUI) jumped 44%, how crypto OI and leverage amplified the rally, what the pullback means, and how to trade SUI on WEEX.
CFTC Chair Calls for "Mass Tokenization"! Wall Street Faces Three Barriers to Full On-Chain Adoption
Is the 1 Billion POL Burn Just a Joke?
WEEX Exclusive:Bitcoin Pulls Back From $87,000| WEEX TradFi Daily Brief (September 24, 2026)
Bitcoin Pulls Back From $87,000| WEEX TradFi Daily Brief (September 24, 2026)
Bitcoin pulled back from about $87,000 to about $84,000, with Ethereum near $2,680. S&P Global PMI on September 23 ET far exceeded forecasts. The 10-year yield broke above 5.00%, while the 5-year and 30-year touched highs last seen in 2007 and 2004. The S&P 500 and Nasdaq slipped. Energy moved with oil and crypto-treasury stocks followed bitcoin lower. Investors await earnings from COST, BB, and others.
OKX Star Points Out THORChain TSS + Validator Model Lacks Decentralization
Payward, the parent company of Kraken, invests billions in financial infrastructure
Bloomberg analyst warns 5% U.S. 10-year yield may reduce Bitcoin appeal
Shielded Bitcoin: the proposal that aims to bring privacy without changing BTC's code
What is CBDC? Governments Push for Development of Central Bank Digital Currencies
Backpack CEO Plans to Bring the Entire Stock Market to Solana


